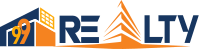
There is a special feeling that comes with owning a home. After years of saving, comparing properties and planning finances, finally getting the keys feels like the finish line.
In reality, it is the beginning of a new financial chapter.
Homeownership comes with costs that extend well beyond the purchase price — from the home loan EMI and registration charges to maintenance, repairs, insurance, utility bills and property taxes. The good news is that many of these expenses can be planned for.
A financially comfortable home is not necessarily the one with the lowest purchase price. It is the one whose total cost of ownership fits comfortably into your long-term budget.
Here are some practical ways to manage those costs.
Property Law Alert : SC Redefines Ownership Rules
1. Look Beyond the Property Price
The advertised price of a home is only one part of the purchase equation.
Before finalising a property, calculate the complete acquisition cost, including:
- Down payment
- Stamp duty
- Registration charges
- GST, wherever applicable
- Home-loan processing and related charges
- Brokerage, if applicable
- Interior and furnishing expenses
- Moving costs
- Society or maintenance deposits
The exact statutory charges vary by state and property type, so buyers should verify the applicable rates before budgeting.
A useful approach is to create a “true purchase cost” sheet before booking the property. This prevents the common mistake of spending most of your savings on the down payment and then relying heavily on loans or credit cards for interiors and other immediate expenses.
99Realty Tip: Keep a separate cash buffer for post-possession expenses rather than treating every rupee saved for the down payment as available for the purchase.
2. Treat Your Home Loan as a Long-Term Financial Commitment
For most Indian buyers, the home loan is likely to be the largest recurring expense associated with the property.
Don’t choose a loan simply because it offers the lowest advertised interest rate. Compare the effective borrowing cost, processing charges, reset mechanisms, prepayment rules and other terms.
Before signing the loan agreement, calculate:
Monthly EMI + maintenance + utilities + property-related expenses = actual monthly housing cost
A longer tenure can make the EMI easier to manage, but it generally means paying interest for a longer period. A shorter tenure can reduce the overall interest burden while increasing the monthly EMI.
The right balance depends on your income stability, existing loans, savings and other financial goals.
And don’t forget to maintain an emergency fund even after making the down payment. A home loan should not leave you without liquidity.
3. Make Your Monthly Home Budget Work Smarter
Once you move in, recurring expenses become part of everyday life.
Electricity, water, maintenance, internet, security, repairs, domestic help and property taxes can collectively become a significant monthly outflow.
Start by tracking your home-related expenses for at least three to six months. This will reveal where your money is actually going.
Simple ways to reduce recurring costs:
Use energy-efficient appliances: Look for the BEE star label when purchasing appliances. The Bureau of Energy Efficiency says its Standards & Labelling programme generated estimated savings of 89.80 billion units of energy in 2025, highlighting the financial importance of energy efficiency at scale.
Control standby consumption: Switch off appliances that aren’t being used instead of leaving them permanently on standby.
Fix leaks quickly: A dripping tap or leaking pipe may appear insignificant, but small problems can turn into larger water bills and expensive repairs.
Review subscriptions: Internet upgrades, OTT services and smart-home subscriptions can quietly increase monthly expenses.
4. Create a Dedicated Home Maintenance Fund
One of the biggest mistakes new homeowners make is treating repairs as unexpected events.
They aren’t.
Paint eventually needs refreshing. Plumbing requires attention. Appliances fail. Waterproofing may need work. Electrical components wear out. Society maintenance charges can also increase over time.
Instead of waiting for a major repair to disrupt your finances, create a home maintenance fund and contribute to it every month.
You can also divide expenses into three categories:
Routine: Cleaning, servicing and minor repairs.
Periodic: Painting, appliance replacement, waterproofing and furniture maintenance.
Emergency: Plumbing failures, electrical problems, major leakage or structural repairs.
This approach turns a large, stressful expense into a manageable financial commitment.
5. Don’t Leave Tax Benefits on the Table
Home loans can offer tax benefits, but the actual benefit depends on the taxpayer’s circumstances and the tax regime selected.
Under the Income Tax Department’s current guidance, eligible taxpayers under the old tax regime can claim up to ₹2 lakh as a deduction for interest on a qualifying self-occupied home loan under Section 24(b). Eligible housing-loan principal repayment can also form part of the ₹1.5 lakh combined Section 80C limit.
However, tax treatment differs between the old and new tax regimes and between self-occupied and let-out properties.
So don’t make a property decision purely because of a potential tax deduction. Instead, calculate the benefit based on your actual income, loan structure and tax regime.
Keep these documents organised: loan certificates, interest statements, registration documents, receipts and other relevant property records.
6. Keep an Eye on Government Housing Schemes
Government housing programmes can also influence the affordability equation for eligible buyers.
For example, PMAY-Urban 2.0 continues to be implemented, with government assistance being released for housing projects during FY 2026–27. In September 2026, the Union government sanctioned the first instalment of central assistance for 22,476 houses across 46 projects in Jharkhand under the scheme.
However, eligibility, assistance structure and applicable conditions vary. Buyers should always check the latest official scheme guidelines rather than relying on older articles or social-media claims.
7. Don’t Ignore Insurance and Property Protection
A home represents a substantial portion of a family’s wealth, yet insurance is often overlooked.
Depending on your circumstances, consider appropriate protection for the property and its contents. Homeowners should also understand what their housing society’s insurance covers and what remains their individual responsibility.
For homeowners with a large outstanding loan, adequate life and health insurance can also help protect the family’s ability to continue meeting financial commitments if circumstances change.
8. Turn Unused Space into an Asset
A home can sometimes generate income in addition to providing shelter.
Depending on local regulations, society rules and the property’s configuration, homeowners may explore options such as:
- Renting out an additional room
- Leasing an independent floor
- Renting an unused parking space where permitted
- Using an eligible property for long-term rental income
However, rental income comes with responsibilities including tenant verification, maintenance, taxation and compliance with local rules and society regulations.
The objective should not simply be to generate income, but to ensure that the additional income justifies the associated costs and effort.
9. Work With Your Neighbourhood, Not Against It
Apartment living creates an opportunity to reduce certain costs collectively.
Resident Welfare Associations and apartment communities can negotiate bulk rates for services such as pest control, housekeeping, landscaping, security and maintenance.
Collective purchasing can sometimes provide better pricing than individual arrangements.
But cost-cutting should not come at the expense of safety or essential services. Security systems, fire safety, lifts and critical building maintenance should be treated as necessities rather than areas for aggressive savings.
10. Think About the Home’s Future Value
Owning a home is a long-term financial decision, so maintenance should also be viewed through the lens of future value.
Regular waterproofing, timely repairs, good ventilation, quality fixtures and proper documentation can help preserve the property’s condition.
If you plan to sell or rent the property later, practical improvements generally make more sense than expensive upgrades purely for appearance.
The question before spending on any renovation should be:
Will this improve functionality, reduce future costs or make the property more attractive to future buyers or tenants?
The Bottom Line
Homeownership doesn’t have to become a financial burden after the excitement of possession wears off.
The key is to look at the property as a long-term financial commitment rather than a one-time purchase.
Plan the complete acquisition cost before buying. Keep your EMI manageable. Build a maintenance reserve. Monitor utility expenses. Understand the tax rules applicable to you. Protect the property and periodically review your overall housing budget.
Most importantly, don’t wait for a large expense to arrive before planning for it.
A well-managed home isn’t simply a place to live — it can also become one of the most stable components of a family’s long-term financial plan.
Your home should give you financial security, not take it away.
Disclaimer: The information provided in this article is for general informational and educational purposes only. Home loan rates, taxes, government schemes, regulations and property-related costs may change over time and vary by location and individual circumstances. Readers are advised to verify the latest information with relevant government authorities, lenders or qualified professionals before making financial or property decisions.
Need Help?
Need help evaluating a property or planning your next move in the market?
Reach out to 99 REALTY – your trusted real estate partner for smarter choices.
Subscribe to get updates on our latest posts and market trends.
Join The Discussion