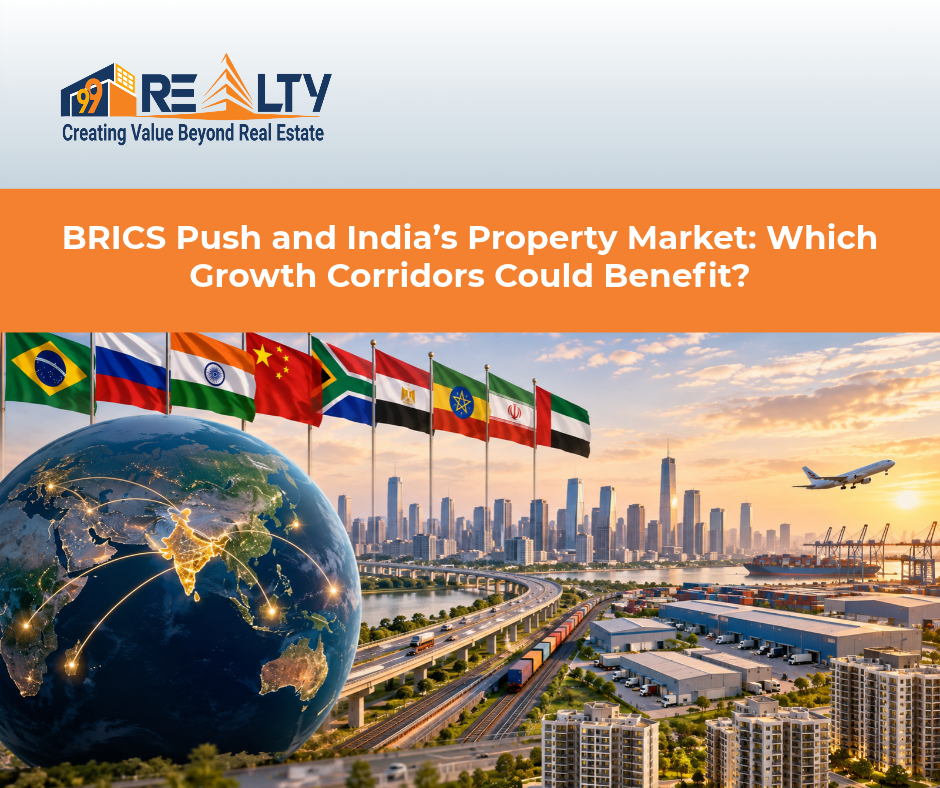
India’s 2026 BRICS presidency has placed greater emphasis on trade, resilient supply chains, industrial cooperation, connectivity and infrastructure. While BRICS is not a real estate programme, these priorities could have an indirect impact on India’s property landscape by strengthening the economic activity that typically drives demand for industrial, logistics, commercial and residential real estate.
The potential link is straightforward: stronger trade and supply chains can encourage manufacturing and logistics investment; new employment centres can increase urbanisation; and growing economic activity can create demand for supporting real estate.
The question for India’s property sector is therefore not whether BRICS will directly push property prices higher, but whether its economic priorities could reinforce some of the country’s existing growth corridors.
Top 10 USP that drive demand and price growth
BRICS’ New Focus on Trade, Infrastructure and Connectivity
The 2026 BRICS New Delhi Declaration places significant emphasis on resilient global value chains, critical infrastructure, industrial capacity and enhanced connectivity. It also highlights the potential of Special Economic Zones (SEZs) to promote trade, investment and industrial cooperation.
The declaration also calls for greater cooperation in trade facilitation and customs, while continuing work on the BRICS Economic Partnership 2030.
These initiatives are important for real estate because global and domestic supply chains require physical infrastructure—factories, warehouses, logistics parks, transport networks, offices and housing for workers and professionals.
However, the impact is unlikely to be immediate or uniform across India. The real estate effect will depend on where actual investment, infrastructure and employment growth materialise.
India’s Logistics Market Already Shows the Connection
India’s industrial and logistics real estate market provides an indication of how economic activity and infrastructure can translate into property demand.
According to Cushman & Wakefield, industrial and logistics leasing across India’s top eight cities reached 36.2 million sq. ft. in H1 2026, an 18% year-on-year increase. Warehousing accounted for 24.3 million sq. ft., or 67% of total leasing, while industrial leasing grew 36% year-on-year to nearly 12 million sq. ft.
CBRE’s H1 2026 data similarly shows that Delhi-NCR, Chennai and Bengaluru accounted for around 60% of total industrial and logistics leasing. Third-party logistics, engineering and manufacturing remained major sources of demand.
This existing demand is important because BRICS-related trade and supply-chain cooperation would build on an ecosystem that is already developing rather than creating one from scratch.
Growth Corridor 1: Delhi-NCR and Western Uttar Pradesh
Delhi-NCR is already one of India’s largest logistics and industrial markets.
Cushman & Wakefield reported that Delhi-NCR accounted for 24% of industrial and logistics leasing across the top eight cities in H1 2026, the largest share among the markets tracked.
The broader NCR ecosystem—including areas around Noida, Greater Noida, Ghaziabad and other peripheral industrial and logistics locations—combines manufacturing, warehousing, expressways and access to one of India’s largest consumer markets.
If trade and supply-chain activity continues to expand, locations with strong freight connectivity and proximity to employment centres could see continued demand for warehouses, industrial facilities, commercial space and housing.
Growth Corridor 2: Chennai–Bengaluru
Southern India’s manufacturing ecosystem makes the Chennai–Bengaluru belt another corridor worth watching.
Chennai recorded a 17% share of India’s top-eight-city industrial and logistics leasing in H1 2026, while Bengaluru remained one of the country’s leading markets.
The corridor’s combination of manufacturing, technology, automotive activity and established logistics infrastructure provides a strong base for further commercial and industrial development.
For real estate, the impact can extend beyond large industrial facilities. New employment clusters can generate demand for rental housing, residential projects, retail and neighbourhood-level commercial infrastructure.
Growth Corridor 3: Mumbai–Pune
The Mumbai–Pune region combines financial services, manufacturing, logistics and access to major transport infrastructure.
Pune accounted for 16% of top-eight-city industrial and logistics leasing in H1 2026, according to Cushman & Wakefield.
The wider corridor also benefits from its relationship with Mumbai’s port and financial ecosystem. As manufacturing and distribution networks evolve, peripheral locations with good road and freight connectivity could become increasingly relevant for industrial and mixed-use development.
Growth Corridor 4: Eastern India
Eastern India could also gain importance as India strengthens domestic logistics and connectivity.
Kolkata remains an important eastern logistics market, while cities such as Jamshedpur and other industrial centres have established manufacturing bases.
For Jharkhand, the opportunity is particularly connected to industrial activity, freight movement and urban expansion, rather than BRICS membership alone. If infrastructure and manufacturing investment increases, the resulting employment and logistics requirements could support demand for industrial land, warehouses, commercial properties and housing.
This makes eastern India’s infrastructure development an important trend for developers and investors to monitor.
Dedicated Freight Corridors Could Strengthen the Story
India’s freight infrastructure is already undergoing a major transformation.
The Eastern Dedicated Freight Corridor runs 1,337 km from Ludhiana to Sonnagar, while the Western Dedicated Freight Corridor runs 1,506 km from Dadri to Jawaharlal Nehru Port Terminal. Both have been commissioned.
Recent reporting indicates that the two DFCs are carrying around 14% of India’s rail freight despite representing only about 4% of the railway network, highlighting their growing importance to freight movement.
For real estate, freight corridors can create opportunities around logistics parks, warehousing clusters, industrial nodes and supporting urban development.
The important point is that connectivity does not automatically create property demand. Demand becomes stronger when connectivity is accompanied by actual industrial investment, businesses, employment and population growth.
What Could This Mean for Residential Real Estate?
The residential impact of BRICS-related economic activity would most likely be indirect.
If manufacturing facilities, logistics parks, SEZs and service businesses expand, they can create new employment centres. Housing demand may then develop around those centres.
This could increase the relevance of:
- Affordable housing near industrial clusters
- Mid-income housing near employment hubs
- Rental housing for mobile workers and professionals
- Plotted developments along expanding urban edges
- Mixed-use projects near transport nodes
- Retail and neighbourhood commercial developments
In other words, the strongest residential opportunities may emerge after economic activity reaches a location, rather than simply because a major infrastructure project has been announced.
What Should Real Estate Stakeholders Watch?
For developers, investors and homebuyers, the BRICS story should therefore be viewed through measurable indicators.
Key signals include:
1. Industrial investment: Are manufacturers establishing or expanding facilities?
2. Logistics demand: Are warehouse and industrial leasing volumes increasing?
3. Freight connectivity: Are highways, rail freight corridors, ports and multimodal terminals improving?
4. Employment creation: Are new projects generating sustained local employment?
5. Urban infrastructure: Are roads, public transport, utilities and social infrastructure keeping pace?
6. Residential absorption: Is actual housing demand increasing rather than simply land speculation?
These indicators provide a more practical framework than treating BRICS itself as a property-market catalyst.
The Bigger Real Estate Picture
India’s BRICS presidency has strengthened the focus on trade, supply chains, infrastructure, industrial cooperation and connectivity. At the same time, India’s domestic freight and logistics infrastructure is expanding rapidly.
The result could be a gradual reshaping of India’s economic geography.
For real estate, the opportunity lies where trade meets infrastructure, infrastructure meets industry, and industry meets urbanisation.
BRICS may not directly determine India’s next property hotspots. But if its initiatives translate into stronger trade, investment and supply-chain networks, they could reinforce the economic foundations of several existing and emerging growth corridors.
For the real estate industry, the bigger question is therefore not simply:
“Where is property developing today?”
It is:
“Where are infrastructure, industry, employment and connectivity coming together to create tomorrow’s urban demand?”
That may be where India’s next generation of real estate growth corridors begins to take shape.
Sources: Government of India/Prime Minister’s Office, Ministry of Railways/PIB, CBRE, Cushman & Wakefield and Indian Express.
Need Help?
Need help evaluating a property or planning your next move in the market?
Reach out to 99 REALTY – your trusted real estate partner for smarter choices.
Subscribe to get updates on our latest posts and market trends.
Join The Discussion