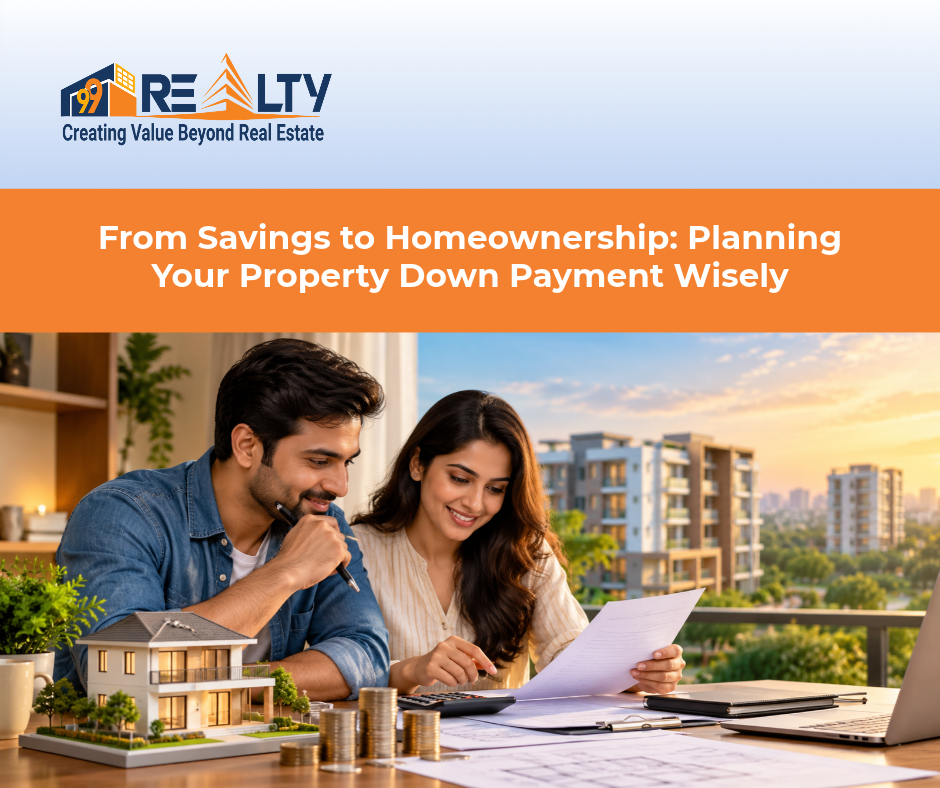
For many Indian families, buying a home is a dream years in the making. It begins with conversations around location, budget and lifestyle, followed by property visits, comparisons and discussions about home loans. Yet, one of the most crucial parts of the journey often receives less attention than it deserves: the down payment.
While a home loan can finance a substantial portion of a property’s cost, buyers are generally expected to contribute a part of the amount from their own funds. This initial contribution influences the loan requirement, monthly EMI and the financial flexibility a family retains after purchasing its home.
So, how much should you save? And is making a larger down payment always the smarter choice? The answer lies in finding the right balance between owning your dream home and protecting your financial future.
Avoid These Real Estate Trap Zones in India Now
Understanding the Down Payment: Your First Investment in Homeownership
A down payment is the portion of the property’s purchase price that a buyer pays using personal funds rather than a home loan. The remaining eligible amount may be financed by a bank or housing finance company, subject to its assessment and lending policies.
For example, consider a property priced at ₹50 lakh. If a buyer contributes ₹10 lakh towards the purchase, the remaining ₹40 lakh would need to be arranged through a home loan or other eligible sources.
However, the actual contribution required can vary depending on the property’s value, the lender’s loan-to-value limits, the buyer’s eligibility and the terms of the transaction.
The important thing to remember is that loan eligibility and affordability are two different things. A lender may approve a particular loan amount, but that does not necessarily mean the resulting EMI will fit comfortably into your household budget.
How Much Down Payment Should You Aim For?
There is no single percentage that works for every homebuyer. The required contribution depends on the property’s price and the applicable lending rules. As a broad planning estimate, buyers may need to arrange around 10%–25% of the property value from their own resources, although the actual requirement can fall outside this range in individual cases.
Here is a simplified illustration:
| Property Value | Illustrative 20% Contribution | Remaining Amount |
|---|---|---|
| ₹30 lakh | ₹6 lakh | ₹24 lakh |
| ₹50 lakh | ₹10 lakh | ₹40 lakh |
| ₹75 lakh | ₹15 lakh | ₹60 lakh |
| ₹1 crore | ₹20 lakh | ₹80 lakh |
These figures are illustrative, not guaranteed loan offers. Actual lender funding depends on applicable regulatory limits, property valuation and individual eligibility. The remaining amount is not a confirmation of loan approval.
Rather than chasing a fixed percentage, buyers should calculate how much they can contribute without compromising essential expenses, emergency savings and long-term financial goals.
The Hidden Costs Beyond the Property Price
One of the most common home-buying mistakes is preparing only for the down payment. In reality, purchasing a property involves several additional expenses that can increase the upfront financial requirement.
These may include:
- Stamp duty and registration: Government charges associated with legally registering the property, which vary by state and transaction.
- GST, where applicable: Certain under-construction residential properties may attract GST under applicable rules.
- Loan processing and legal charges: Fees associated with processing the home loan and completing relevant checks.
- Brokerage: Applicable if a real estate intermediary is engaged on chargeable terms.
- Interiors and furnishings: Expenses for essential furniture, fittings, appliances and personalisation.
- Maintenance deposits and moving costs: Initial payments and relocation expenses that may arise around possession.
For instance, a buyer planning to purchase a ₹50 lakh home should not assume that having ₹10 lakh automatically makes them financially ready. The additional charges must be estimated separately, based on the property’s location, category and transaction terms.
A detailed budget helps prevent last-minute borrowing and makes the entire purchase process more predictable.
Bigger Down Payment or Smaller EMI? Finding the Balance
Putting more money upfront reduces the amount borrowed. This can lower the EMI and reduce the total interest payable over the loan tenure, assuming other loan terms remain comparable.
However, there is another side to the decision.
If a buyer commits nearly all available savings towards the property, they may have little money left for unexpected medical expenses, temporary income disruptions or essential repairs. A home should provide security, not create financial vulnerability.
A smaller down payment may preserve liquidity, but it usually means a larger loan and potentially higher interest costs. The decision should therefore consider both the immediate purchase and the years of repayment that follow.
The most sensible approach is to calculate the EMI under different down-payment scenarios and compare the savings in interest against the cash reserve that would remain available.
Build Your Down Payment Before You Begin Property Hunting
A successful home purchase often begins long before the first site visit. A planned savings strategy gives buyers a realistic understanding of their budget and helps narrow their property search.
Start by defining a target purchase price and estimating the total upfront requirement, including transaction charges. Next, subtract the savings you can comfortably allocate without touching your emergency reserve.
The remaining amount becomes your savings goal.
If you need ₹8 lakh over four years, for example, you would need to set aside approximately ₹16,667 every month, excluding interest or investment returns. If that amount is difficult to manage, you could extend the timeline, adjust the property budget or review your monthly expenses.
For a goal that is only a few years away, prioritise suitable savings options that match your time horizon and risk tolerance. Avoid relying on uncertain investment returns to fund a payment that must be made on a fixed date.
First-Time Buyers Need a Different Kind of Preparation
For first-time buyers, the challenge is often balancing a growing career, family responsibilities and the desire to own a home. It can be tempting to stretch the budget for a property that appears perfect today.
But the real test begins after possession, when monthly EMIs arrive alongside groceries, school fees, transport, insurance and other household commitments.
Before committing, review your existing loans, credit obligations and likely future expenses. Consider whether the EMI would remain manageable if household costs increased or income temporarily declined.
It is equally important to understand the property documents, the developer’s commitments and the applicable RERA registration details for projects where registration is required. Financial readiness and property due diligence should go hand in hand.
Avoid These Common Down Payment Mistakes
A few decisions can make an otherwise promising purchase unnecessarily stressful.
Draining emergency savings: Keep a separate financial buffer for unexpected expenses rather than committing every available rupee to the purchase.
Borrowing to fund the contribution: A personal loan or credit card debt can add costly repayments just as a home loan begins. Review the complete debt burden before considering any such arrangement.
Ignoring future expenses: Account for maintenance, utilities, insurance and essential furnishing costs alongside the EMI.
Choosing a property based only on loan approval: A bank’s eligibility assessment is not a substitute for your own affordability calculation.
Rushing because of perceived urgency: Evaluate the price, documents, payment schedule and contractual terms before making a commitment.
Your Dream Home Deserves a Thoughtful Beginning
A down payment is more than the first cheque in a property transaction. It reflects the preparation behind a major life decision.
The right plan is not necessarily the one that gets you into a home fastest. It is the one that allows you to own your home while continuing to save, meet family responsibilities and pursue future goals.
At 99Realty, we believe that informed homebuyers make more confident decisions. Explore properties that match your needs, compare your options carefully and understand the financial commitment before taking the next step.
Because buying a home is not just about finding the right address. It is about building a future you can afford to enjoy.
Need Help?
Need help evaluating a property or planning your next move in the market?
Reach out to 99 REALTY – your trusted real estate partner for smarter choices.
Subscribe to get updates on our latest posts and market trends.
Join The Discussion